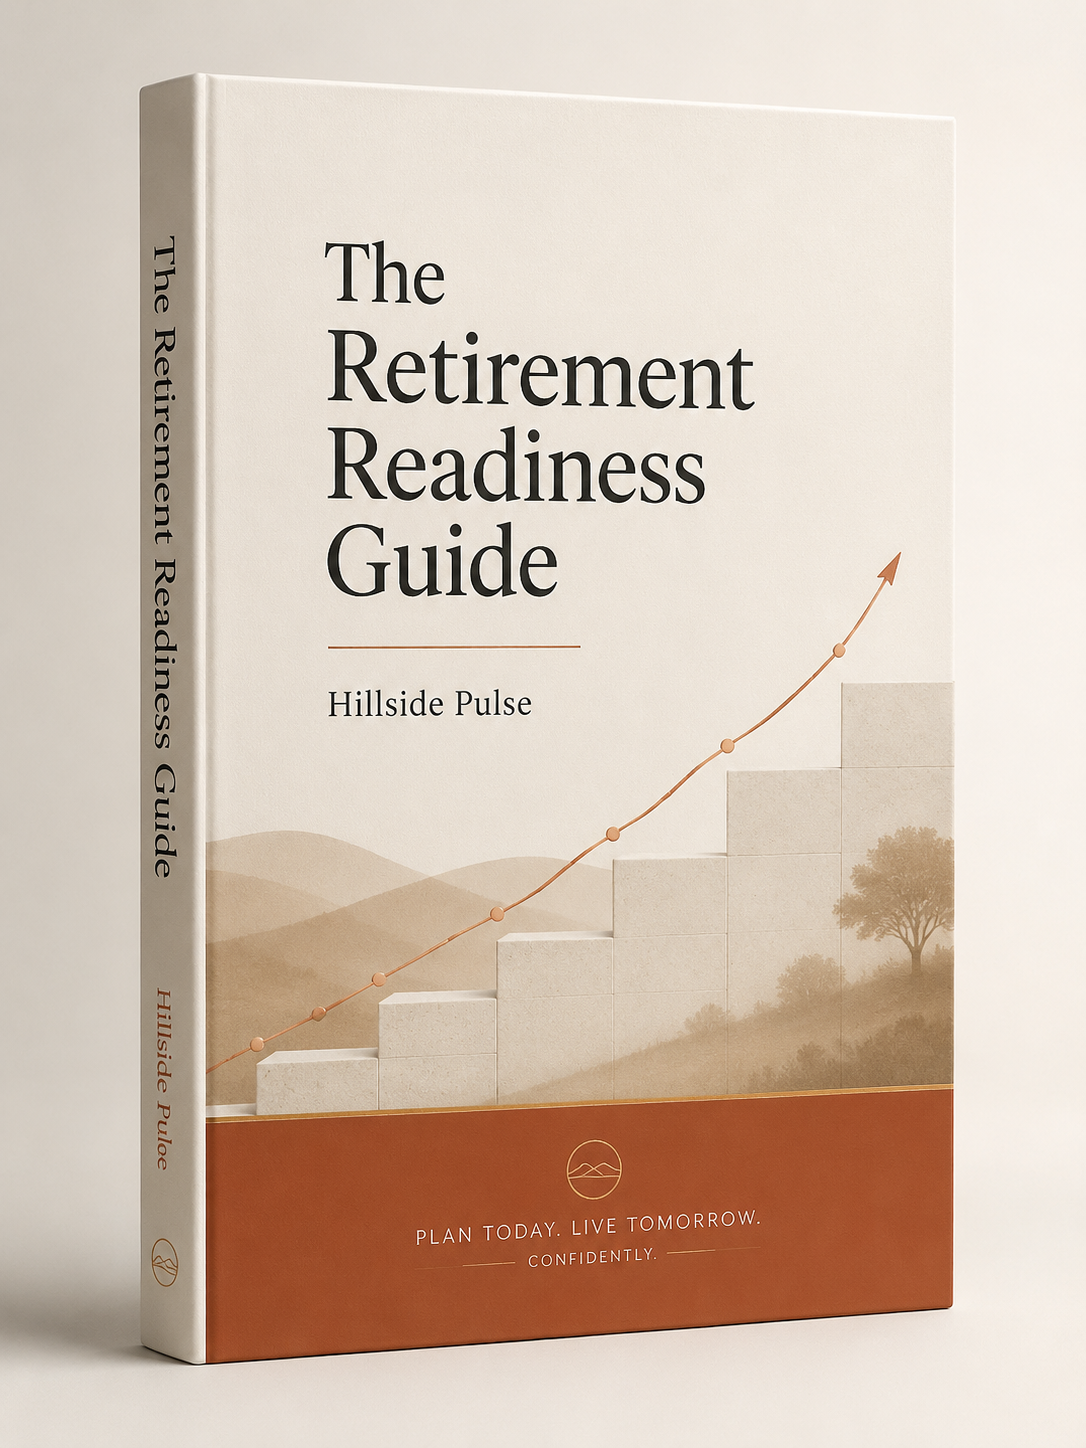
The Retirement Readiness Guide

Plan the retirement you actually want.

A clear, jargon-free guide to mapping your retirement income, choosing a withdrawal strategy, and budgeting for healthcare — so you can stop worrying whether your savings will last and start planning with confidence.

PDF · 112 pages · 30-day guarantee · Instant download

The Retirement Readiness Guide

Deep read · The cost of not having a plan

The Hardest Part of Retirement Isn’t Saving. It’s Knowing When You Have Enough.

Most people spend their working lives being told to save more. Almost no one is told what to actually do with that money when the paychecks stop. The result is a quiet, persistent anxiety: a balance in an account, and no clear answer to the only question that matters — will it last?

The good news is that retirement readiness is not a mystery reserved for people with advisers on retainer. It is a sequence of answerable questions. How much will you spend? Where will the income come from, and in what order should you draw it? What happens to your plan if markets fall in your first few years? What will healthcare actually cost? Each of these can be estimated, written down, and stress-tested — and once they are, the anxiety tends to fade.

Why a Number Isn’t a Plan

You have probably seen the headlines: “You need $1.5 million to retire.” These figures make for good clickbait and poor planning. A single number ignores when you retire, how long you live, what you spend, where you live, and how your income is structured. Two people with identical savings can have completely different levels of readiness depending on their spending and their withdrawal strategy.

Readiness is better understood as a relationship between three things: what you reliably spend each year, what guaranteed income you have coming in, and how much your portfolio needs to cover the gap. Once those three are on paper, the abstract question “do I have enough?” becomes a concrete one you can answer and revisit each year.

“A retirement plan isn’t a number you hit once. It’s a relationship between your spending and your income that you revisit every year.”

The Order You Withdraw Matters More Than You Think

The sequence in which you draw from taxable accounts, tax-deferred accounts, and tax-free accounts can meaningfully change how long your money lasts and how much tax you pay over a retirement. So can the timing of when you claim guaranteed income. These are not exotic optimisations — they are decisions every retiree makes, knowingly or not. Making them deliberately is most of the difference between a plan that holds and one that frays.

The full guide walks through income mapping, withdrawal sequencing, healthcare budgeting, and a year-by-year readiness checklist across 112 pages. Get it here for $39.

Perhaps the most underappreciated risk is the order in which returns arrive. A poor run of markets in the first few years of retirement — while you are drawing down — does far more damage than the same poor run a decade later. The guide shows how to build a simple buffer against this “sequence-of-returns” risk without resorting to complicated products or market timing. None of it requires you to predict anything. It requires you to plan for the range of things that could happen.
See the difference

Without a plan vs. with a plan

Drag the handle to compare a retirement drawn down on guesswork against one mapped out with Hillside Pulse. Same savings — different outcome.

Without a planWith Hillside Pulse

Illustrative projection for explanation only. Not a forecast of any individual result. Investment returns are not guaranteed.

Table of contents

What you’ll work through

Seven chapters, 112 pages, and a set of worksheets that turn a vague worry into a written, year-by-year plan.

Chapter 01

Defining Your Retirement

What “enough” means for you specifically — lifestyle, timing, and the spending number that everything else is built around.

Chapter 02

Mapping Your Income

Inventory every source — guaranteed income, pensions, portfolio, part-time work — and see the gap your savings actually need to cover.

Chapter 03

Choosing a Withdrawal Strategy

Fixed-percentage, guardrails, and bucket approaches explained in plain language, with a worksheet to pick the one that fits you.

Chapter 04

Sequence-of-Returns Risk

Why the first five years matter most, and how to build a simple cash buffer that protects your plan from an early downturn.

Chapter 05

Healthcare & Later-Life Costs

Realistic estimates for medical, dental, and long-term care — the expenses most plans quietly underestimate.

Chapter 06

Taxes & Account Order

How the order you draw from taxable, tax-deferred, and tax-free accounts changes how long your money lasts.

Chapter 07

Your Annual Readiness Review

A one-page checklist to revisit each year so your plan stays current as markets, spending, and life change.

Bonus

The Worksheet Pack

Every worksheet from the guide as fillable, printable pages — income map, withdrawal planner, and the annual review.

Margaret Ellison

About the author

Margaret Ellison, CFP®

Retirement Planner · Former Financial Educator

Margaret Ellison spent more than two decades guiding individuals and couples through the transition from working life to retirement, first inside a regional advisory practice and later as an independent financial educator. She holds the Certified Financial Planner designation and has run hundreds of pre-retirement workshops.

The Retirement Readiness Guide grew out of the questions she heard most often — not from people who lacked savings, but from people who had saved diligently and still had no idea whether it was enough. Her goal was to put a structured, jargon-free planning process into the hands of anyone, without a meeting or a sales pitch.

20+

Years in retirement planning

CFP®

Certified Financial Planner

300+

Pre-retirement workshops led

Common questions

Before you buy

Is this financial advice?

No. The Retirement Readiness Guide is educational. It gives you a structured process and worksheets to plan your own retirement, but it does not provide personalised financial advice or recommend specific products. For advice tailored to your situation, consult a qualified financial adviser.

I’m not great with numbers — is this too technical?

Not at all. Everything is written in plain language, and every calculation is supported by a step-by-step worksheet. If you can fill in a few boxes and do basic arithmetic (or use a calculator), you can complete the entire process.

How close to retirement do I need to be?

The guide is most useful in the ten years before and the first years after you stop working, but the planning framework helps at any stage. The earlier you map your income and spending, the more options you have.

What format is it, and how do I get it?

PDF, 112 pages, including fillable worksheets. An instant download link is sent to your email immediately after payment. It reads on any device and prints cleanly. Any issues, email contact@hillsidepulse.com.

What is your refund policy?

A 30-day money-back guarantee, no questions asked. Email contact@hillsidepulse.com with the subject “Refund Request” within 30 days of purchase and we’ll refund you within 5 business days. See our Refund Policy for full terms.

Does it apply outside the United States?

The planning framework — income mapping, withdrawal strategy, sequence risk, healthcare budgeting — applies anywhere. Specific tax and account examples use United States conventions, so readers elsewhere should adapt those details to their local rules.

Get the guide

Stop wondering. Start planning.

Turn a vague worry about retirement into a written, year-by-year plan you can revisit with confidence — in an afternoon, with nothing but the worksheets in this guide.

  • Map your retirement income, source by source
  • Choose a withdrawal strategy that fits you
  • Protect against an early-years market downturn
  • Budget honestly for healthcare and later-life costs
  • A one-page annual readiness review checklist

$39

One-time payment · PDF, 112 pages · Instant download

Get the Guide — $39

✓ 30-day money-back guarantee · No questions asked

Educational content only. Not personalised financial advice. See Terms and Refund Policy.

Educational content only. Not personalised financial advice. All investing involves risk, including the potential loss of principal. Individual results vary.

The Retirement Readiness Guide is an educational product. Nothing in it constitutes personalised financial advice or a recommendation to buy, sell, or hold any security, product, or strategy. Retirement and investment outcomes depend on factors specific to your situation, and investment returns are not guaranteed. Projections and illustrations are for explanation only and do not predict any individual result. Please consult a qualified financial adviser before making any retirement or investment decision. Individual results vary.

DRAGONS AGENCY LLC · Business address: 222 S Main St, Salt Lake City, UT 84101